Thirty percent of the contract paid out before a single wall is standing. That is what a front-loaded draw schedule can look like, and many owners sign one without noticing. On a $420,000 build, that is about $126,000 of your loan in the builder's account while your lot still shows only a slab and a stack of lumber. If the builder stalls, walks away, or fails to pay the framing crew, you have little left to finish the house with.
A construction loan never pays the builder all at once. The lender releases money in draws, and each draw is tied to work completed and verified. How those draws are spaced decides who is ahead of the money, the builder or you. Below, the three common approaches go head to head, followed by what to collect every time money moves.
Three draw schedules side by side
| Criterion | Balanced milestone schedule | Front-loaded schedule | Monthly percentage-of-completion |
|---|---|---|---|
| How money is released | At 5 to 7 defined stages (foundation, dried-in, rough-ins, drywall, trim, final) | Large share at deposit, site work and foundation | Once a month, based on the share of each budget line completed |
| Who is ahead of the money | The owner, slightly | The builder, often by a wide margin | Roughly even, if inspections are honest |
| Verification | Inspector confirms a clear milestone | Early milestones are easy to reach, so the inspection proves little | Inspector estimates percentages line by line |
| Lien waiver rhythm | One set per stage | Same, but the early waivers cover little actual work | One set per month, more paperwork |
| Retainage | Commonly 5 to 10% held to final | Often none | Commonly 5 to 10% held to final |
| Risk to the owner | Low | High | Low to moderate |
| Typical fit | Most custom homes built from a stock plan | Rarely justified | Larger or longer builds |
Risk to the owner
Verdict: the balanced milestone schedule wins clearly.
The goal of any schedule is simple: the value built on your lot should always be equal to or greater than the money paid out. A balanced schedule follows the real cost curve of a wood-frame house. Here is an illustration for a $420,000 contract, roughly what a builder might charge in 2025 to 2026 for a 2,500 to 3,000 sq ft home in a mid-cost market. Your own figures will differ.
| Draw | Milestone | Typical range | Example |
|---|---|---|---|
| 1 | Foundation: site work, footings, slab or basement walls, underground plumbing | 10–15% | $50,400 (12%) |
| 2 | Framing dried in: roof sheathed, windows set, house wrap on | 20–25% | $92,400 (22%) |
| 3 | Rough-ins passed: plumbing, electrical, HVAC, plus roofing and exterior | 15–20% | $75,600 (18%) |
| 4 | Insulation and drywall | 12–15% | $63,000 (15%) |
| 5 | Trim, cabinets, flooring, fixtures | 15–20% | $75,600 (18%) |
| 6 | Final: certificate of occupancy, punch list done | 10–15% | $63,000 (15%) |
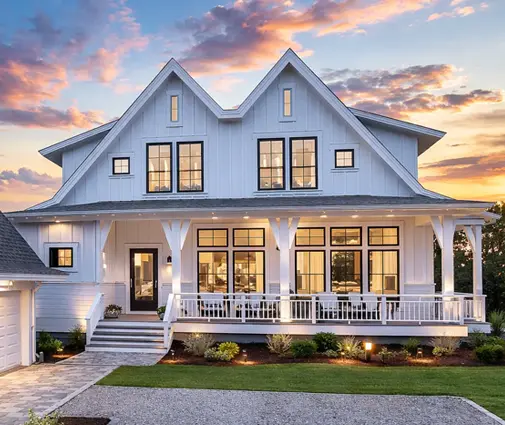
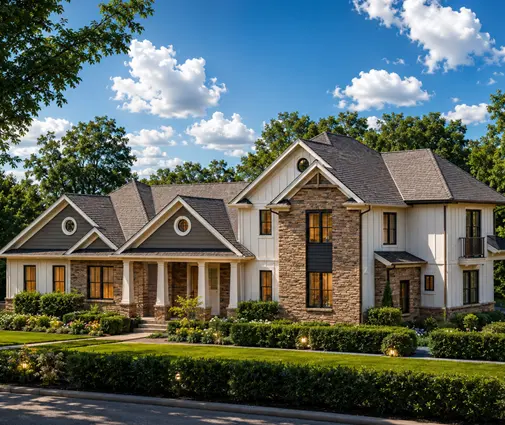
The foundation draw is where plans differ the most. A slab-on-grade ranch in Texas or Georgia keeps draw 1 small, while a full basement in Ohio or Minnesota can push it well past 15%. A plan like this 5-bedroom Colonial-Craftsman with a basement and 2,853 sq ft puts more money into the ground than a slab home of similar size, and that should show up in the schedule. If you are comparing house plans with a basement, ask the builder to split the foundation into two draws (footings and walls, then backfill and slab) instead of inflating it.
A front-loaded schedule breaks the rule. It is sometimes presented as "mobilization" or "material deposits," but if the builder needs a lot of cash before framing, ask why. A small deposit for engineered trusses or windows can be reasonable. A third of the contract is not.
Builder cash flow
Verdict: monthly draws are easiest on the builder; a balanced milestone schedule is fair enough for most.
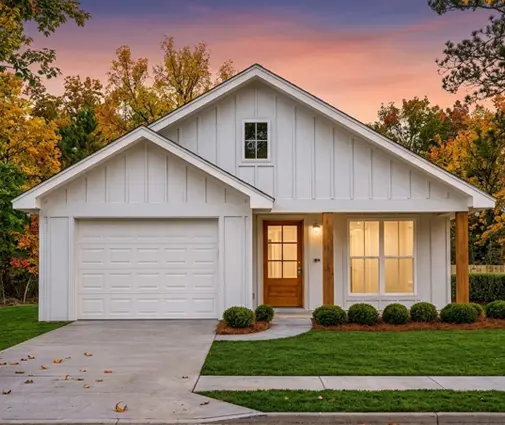
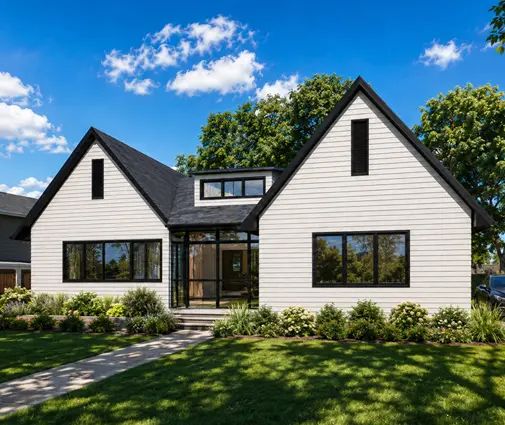
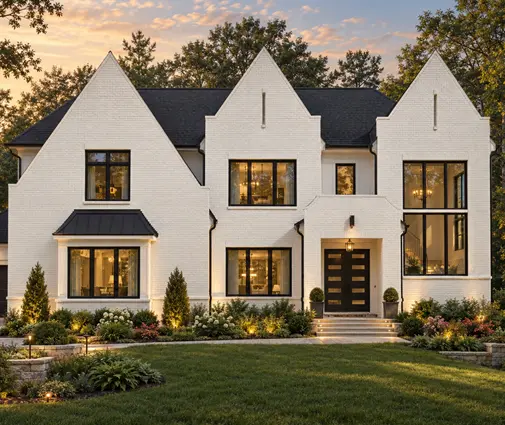
Builders pay subcontractors and suppliers before they get reimbursed, so a long gap between draws strains their cash. On a compact one-story home, such as this 3-bedroom Modern Farmhouse ranch with 1,707 sq ft and a 2-car garage, the stages pass quickly and six draws are plenty. On a large or complex build, the gap between dried-in and drywall can stretch for months. A 6,713 sq ft Modern Tudor with five bedrooms and a basement is the kind of project where monthly draws, or eight to ten milestones, keep good subs on the job. A fair builder will not ask to be ahead of the money; they will ask not to fall too far behind it.
How progress is verified
Verdict: milestones are easier to verify than percentages.
When the builder requests a draw, the lender sends a draw inspector, usually a third party, to the site. The inspector checks that the stage is really complete, takes photos and reports to the lender. Expect a fee per visit, often around $100 to $250 in 2025 to 2026, sometimes rolled into the loan. Many lenders also order a title update before each draw to make sure no new liens were filed. From request to funding, a few business days to about two weeks is common.
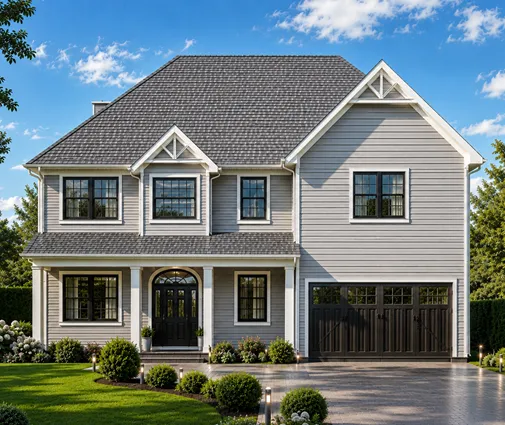
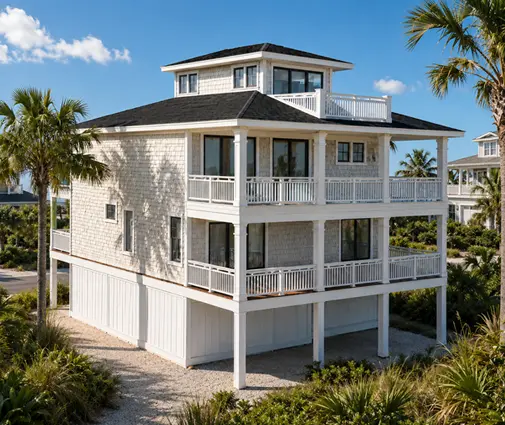
"Roof sheathed and windows in" is a yes-or-no question. "Plumbing 60% complete" is a judgment call, which is why monthly percentage schedules depend more on the inspector's experience. Either way, the inspector works for the lender, not for you. Walk the site yourself before you sign off on a draw, and compare what you see with the plans. On a complex house like this 4-story coastal home with 2,722 sq ft, where pilings, elevated framing and wind-rated connections matter, a private inspector of your own can be worth the fee.
Lien waivers at every draw
Verdict: all three schedules need them; milestones make them easiest to track.
If the builder takes your money and does not pay the lumber yard or the electrician, those parties can file a mechanic's lien against your house, even though you paid in full. Lien waivers are how you prevent that. There are four kinds:
- Conditional waiver on progress payment: the builder or sub gives up lien rights for this draw, but only once the payment actually clears. Collect it before the draw is released.
- Unconditional waiver on progress payment: confirms the payment was received. Collect it after the funds clear, usually with the next draw request.
- Conditional final waiver: covers the last payment, effective when it clears.
- Unconditional final waiver: no more claims, ever. Collect it from everyone before releasing retainage.
Get them not just from the general contractor, but from the major subs and suppliers: foundation, framing, lumber, roofing, plumbing, electrical, HVAC, drywall and cabinets. A simple rule works well: the next draw is not released until unconditional waivers for the previous one are in hand. Never sign an unconditional waiver yourself, and never accept one from someone who has not been paid yet. Some states, including California and Texas, require specific statutory wording, so check with your lender, title company or a local construction attorney.
Retainage
Verdict: milestone and monthly schedules with retainage protect you best.
Retainage means the lender or owner holds back a share of each draw, commonly 5 to 10%, until the job is finished. It gives the builder a reason to complete the punch list and keeps a cushion if something goes wrong. It is released after the certificate of occupancy, a final inspection, and the unconditional final waivers. Some states limit how much can be withheld or how fast it must be paid, so confirm the rules locally. Front-loaded schedules rarely include retainage, which removes one more layer of protection.
Disputed or delayed draws
Verdict: the clearer the milestone, the faster the dispute ends.
Draws get held up for predictable reasons: the inspector says a stage is not done, a waiver is missing, a lien was filed, the title update shows a problem, or change orders pushed the budget over the loan amount. When it happens:
- Ask the lender for the inspection report and the exact reason for the hold.
- Meet the builder on site and agree in writing on what remains to finish the stage.
- If the work is mostly done, ask whether the lender will fund a partial draw.
- If a lien was filed, require the builder to pay the claimant and get a release, or bond it off, before any more money moves.
- If change orders created a gap, cover it from your own funds or a loan modification; do not let the builder borrow from later stages.
Your contract should already say how long the lender has to fund, how long you have to dispute, and what happens if the builder stops work. Bigger homes with many trades, like this one-story Modern Craftsman with 4 bedrooms and 3,237 sq ft or this 2-story Modern Farmhouse with 2,905 sq ft, have more waivers to collect and more chances for a missing one to hold up a draw.
Who should choose what
- Most families building a single-family home from a stock plan: a balanced milestone schedule with 5 to 7 draws, 5 to 10% retainage, and waivers collected every time. Simple one-story plans fit this perfectly.
- Owners of large, long or complex builds: monthly percentage draws or 8 to 10 milestones, with a strong inspector and a careful budget line by line.
- Basement homes in the North and Midwest: a milestone schedule with the foundation split into two draws.
- Anyone offered a front-loaded schedule: push back, cap any deposit, ask for a payment bond or proof of materials ordered, and talk to your lender before you sign.
- Every owner: walk the site before each draw, and never release money until the previous waivers are in hand.